Startup Capital Flows to Picks and Shovels of the AI Buildout

Photo: SiliconANGLE

Article

Startup Capital Flows to Picks and Shovels of the AI Buildout

SuryaNovember 20, 20265 min read

Fig Security's Elastic partnership and Boltz's $110M raise show startups winning by plugging into platforms and research niches rather than building broad new categories.

The common thread in this week's startup news is that capital and partnership value are flowing to companies that tighten integration with established platforms and clinical pipelines rather than companies trying to stand alone. Fig Security is tying its detection-coverage mapping to Elastic Security, and Boltz has raised $110 million for AI models aimed at pharmaceutical researchers. Both are narrow, functional positions in a market where the adjacent incumbents keep getting larger.

Distribution beats standalone category creation

Fig Security's announcement, reported by SiliconANGLE, frames the deal around visibility: security teams gain a way to see how data changes affect their detection coverage. The startup's mapping of detection dependencies now integrates with Elastic Security, and the platform offers prebuilt integrations. That is not a new product category. It is a statement that Fig's value is realized inside someone else's console.

For US startups, this is the practical arithmetic of the current market. Security buyers already run a stack, and the cost of adding a separate pane of glass is a harder sale than adding a capability inside an existing one. Partnering with Elastic gives Fig reach it would otherwise have to purchase through sales headcount. The trade is visibility and dependency: Fig's roadmap now has to keep pace with Elastic's.

This pattern matters to US consumers only indirectly, but it matters to the companies they depend on. Detection coverage that fails silently when data changes is an operational risk for banks, retailers and healthcare providers. A startup that makes that failure visible is selling into a real gap, and it is doing so through a channel American security teams already procure from.

Research tooling attracts the largest checks

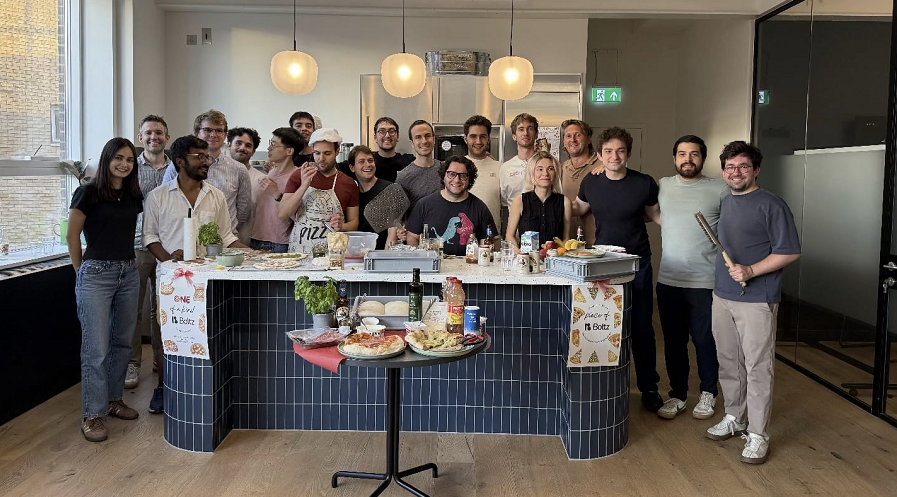
Boltz's $110 million Series A, led by Bessemer with Greycroft, Andreessen Horowitz, Amplify Partners, F-Prime Capital, Hummingbird and others participating as SiliconANGLE reported, is a different expression of the same logic. The company builds AI models for pharmaceutical researchers and says the money will speed up small molecule research. It is not selling a consumer product or a horizontal platform. It is selling into an existing, expensive, heavily regulated workflow.

The size of the round is the signal. A $110 million Series A is a bet that the buyer is not a startup's early adopters but large pharmaceutical research organizations with budgets to match. Those buyers are disproportionately American, and the startup's argument depends on their willingness to fold AI models into discovery work that already has years of validation behind it.

What the two stories share is positioning. Boltz attaches to the research pipeline the way Fig attaches to the security console. Neither is asking customers to change how they work. Both are asking to be embedded in how they already work.

The platform pull is not neutral

The obvious risk in the Fig model is that integration partners are not equals. Elastic sets the integration surface, the release cadence and the commercial terms. Fig gets distribution and credibility, but it also gets a dependency that shows up the moment Elastic changes its platform or decides to build similar mapping itself.

That is not a reason to avoid partnerships. It is a reason to read them accurately. A partnership announcement is evidence of demand for a capability, not proof of durable advantage. The startup's defensibility has to come from something the platform partner cannot easily replicate. In Fig's case that would be the depth of its dependency mapping across data sources, which the announcement gestures at but does not quantify.
For US technology companies, this dynamic is now the default for enterprise software startups. The large platform vendors have consolidated the buyer relationship. Startups that win are increasingly the ones that make the platform more useful, then negotiate a position that survives the platform's own roadmap.

Capital is concentrating on credible buyers

Boltz's investor list is notable for its breadth rather than any single name. A group that includes Bessemer, Greycroft, Andreessen Horowitz, Amplify Partners, F-Prime Capital and Hummingbird is not a collection of seed-stage generalists. It is a consortium assembled around a specific thesis about pharmaceutical research budgets.

The contrast with the broader startup market is instructive. Capital is not scarce for companies that can name a buyer with an existing budget line. It is scarce for companies that need to create the budget first. Fig's partner is a procurement path; Boltz's is a research budget. Both startups are selling into demand that already exists rather than manufacturing it.

That has consequences for the US market. If capital keeps concentrating on startups that attach to established spend, the pipeline of genuinely new categories thins. The companies that do get funded will be more capital-efficient and more dependent on a small number of large customers and partners. That is a stable arrangement until the platform or the buyer changes direction.

The context neither startup controls

The third story logged on this beat is not about a startup at all. The Verge's piece on Nvidia's next moves notes that the company now generates pure profit at a rate of roughly $8,300 every second, and that it recently lost its visionary founder CEO. Nvidia is not a competitor to Fig or Boltz. It is the backdrop.

The AI infrastructure buildout that Nvidia's numbers reflect is the reason Boltz can raise $110 million for AI models aimed at drug research. It is also the reason investors are receptive to any startup with a credible claim on AI-adjacent workflows. When the most profitable company in the sector is printing profits at that scale, capital allocators look for the next layer of exposure.

But the same backdrop cuts the other way. The Verge's framing of Nvidia's challenge as whatever does not rock a mind-bogglingly profitable boat is a reminder that incumbency in this cycle is extraordinarily strong. Startups are not competing with Nvidia. They are operating in a market where the dominant player's margins set expectations for everyone else's capital efficiency.

What to watch

Three things are worth tracking from the material above. First, whether Fig's integration with Elastic produces disclosed customer adoption, since the announcement describes capability rather than named deployments. Second, how Boltz deploys $110 million against pharmaceutical research workflows, and whether the company reports progress in terms measurable to the buyers it is targeting. Third, whether the pattern holds: startups raising and partnering by attaching to existing budgets rather than building standalone categories. If it does, the US startup market in this cycle will look less like a wave of new platforms and more like a set of specialized suppliers to the platforms and pipelines already in place.

More on this beat: Companies on TechManNews.

#startups#venture capital#enterprise security#medical AI#platform partnerships#US technology market

Newsletter

Get Tech News in Your Inbox

The latest AI, gadgets, software and startup stories from TechManNews, delivered every morning - free.