The stories logged on this beat share one thread: the chip economy keeps announcing intentions that do not survive contact with the physical world. Approvals are issued, campaigns are funded, upgrades are launched, and still the observable activity falls short of the paperwork. For US chip companies, investors and buyers, the recurring lesson is that announcements are a weak signal and verification is the scarcer commodity.
The Empty-Office Problem
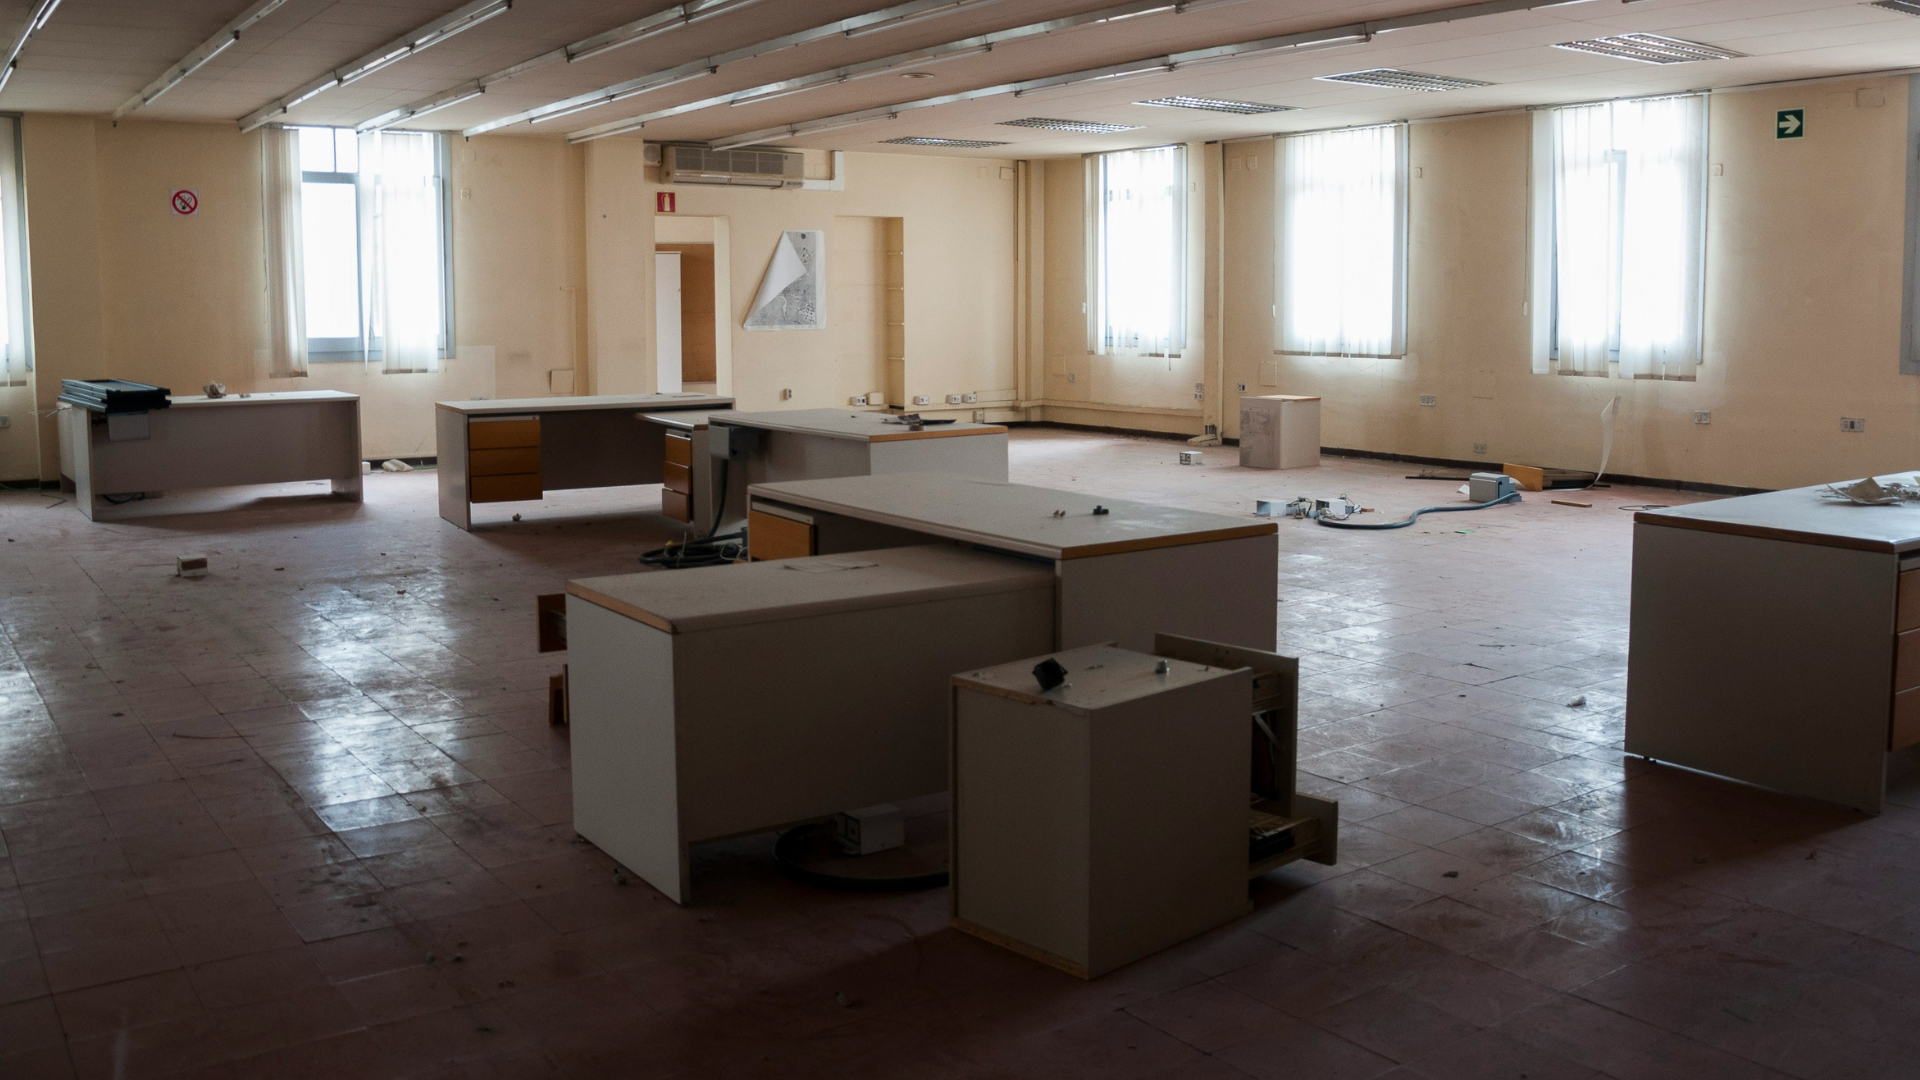
Tom's Hardware reported that two Chinese companies cleared to buy banned Nvidia AI chips, New Matrix and Maginfra, have offices that appear abandoned, and that people in the buildings say they are unfamiliar with the companies or have never seen anyone working there. Both entities were approved to receive H200 chips. That is a concrete, checkable claim, and it matters more than most export-control commentary. Export controls are only as strong as the diligence behind the licenses, and diligence that produces approvals for companies with no visible presence is diligence that a later enforcement action has to clean up.
The implications for US suppliers are not abstract. Every approved shipment to a counterparty with unverifiable operations is a compliance exposure, and the cost of that exposure lands on the American companies selling the hardware, not on the approved buyer. When vetting is thin, the burden shifts downstream to the Nvidia ecosystem and to the distributors and intermediaries in between.
The Campaign That Did Not Land
Wired reported that the biggest pro-AI super PAC network, Leading the Future, backed by Silicon Valley's largest billionaires, spent from a $100 million war chest and took an aggressive stance against AI regulation, and that all of it did not add up to much on Tuesday night. A nine-figure political push that fails to move results is a data point about the limits of spending in this particular cycle, not a verdict on future spending. But it does puncture an assumption that has become comfortable in the chip and AI sector: that money converts reliably into policy outcomes.
For US technology companies, the practical read is that political capital is not a substitute for a coherent policy position. If the industry's loudest spending does not reliably produce the regulatory environment it wants, then the industry's leverage lies elsewhere, in standards, in customer relationships, in supply commitments, and in the unglamorous work of compliance. That is a less flattering story than the funding totals, and it is the one the numbers support.
A Launch That Argued Against Itself
Wired's review of the Apple MacBook Pro M5 noted that Apple announced an updated 14-inch MacBook Pro with the latest M6 chip, and that with the M5 model on sale, the M6 is not obviously worth the upgrade. This is a consumer hardware story on its face, but it is a chip story underneath. Silicon transitions are supposed to create urgency. When the previous generation remains available at a discount and the case for moving is unclear, the chip upgrade cycle stretches out.
That matters to the US market because it is a demand signal for advanced silicon at the consumer end. If buyers see the prior generation as sufficient, the volume and pricing power that chipmakers and PC makers count on from an annual cadence becomes harder to sustain. The M5 and M6 are Apple's own chips, but the pattern generalizes: process and architecture gains that do not translate into a felt difference for users do not move units.