The recent wave of AI agent funding is not one bet. It is at least three, made at different layers of the same stack and at very different check sizes. Manus, Rein Security and Tab, logged on this beat in recent weeks, together show where investors are actually putting money as agentic artificial intelligence moves from demo to deployment.
The platform bet draws the largest checks
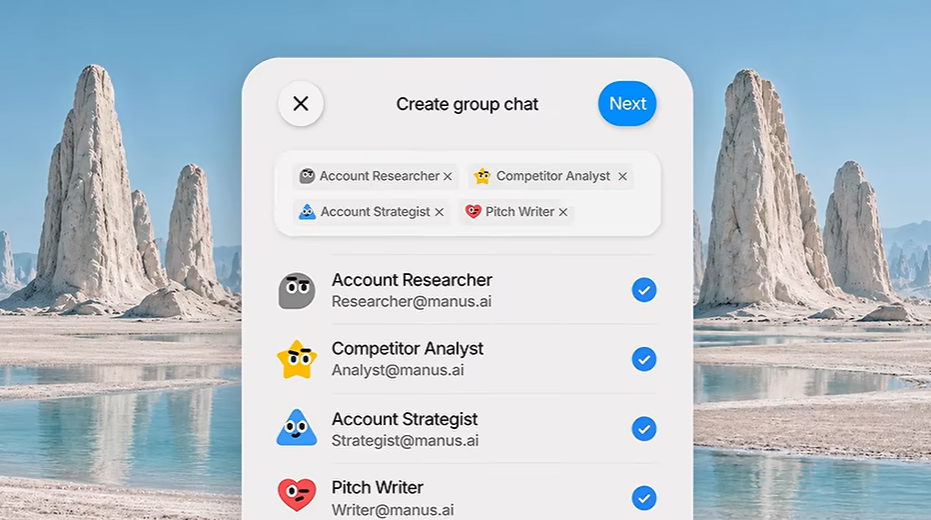
Manus is the clearest example of capital concentrating at the application layer. The Chinese developer of an eponymous AI agent raised more than $500 million, according to SiliconANGLE, in a round led by private equity firm Boyu Capital with participation from Tencent Holdings and several others. SiliconANGLE also noted that Bloomberg had reported a $4 billion valuation last month. That combination - a large private equity lead, a strategic investor in Tencent, and a reported multibillion-dollar mark - is not the profile of an early-stage experiment. It is the profile of a company being funded to scale distribution and compute, not to prove a concept. For US technology companies, the signal is that the platform layer of agents is already consolidating around a small number of well-capitalised names, and that the capital required to compete there is now measured in hundreds of millions, not tens. That raises the cost of entry for US startups hoping to build a general-purpose agent from scratch and shifts the realistic opportunity toward integration, vertical specialization or tooling around the leaders.
The security bet is smaller and more targeted
Rein Security raised $25 million in early-stage funding from Glilot Capital, Sienna Venture Capital, Corner Ventures, Atlacle and RNP Capital Advisors, according to SiliconANGLE. The company says it is trying to help enterprises protect against two distinct security threats relating to agentic AI, and the round is a Series A. The gap between Rein's $25 million and Manus's $500 million-plus is the story here. Security for agents is being funded as a focused, early-stage problem rather than a platform land grab. That is rational: enterprises adopting agents need controls, audit trails and threat detection before they widen deployment, and the buyers are security teams with existing budgets rather than innovation labs. The investor list - several venture firms and advisors rather than a single mega-fund - suggests this is being treated as a specialist category, not a winner-take-all market. For US enterprises, the practical implication is that the tooling to secure agents is being built now, in the same cycle as the agents themselves, rather than as an afterthought.
The consumer bet is being priced on potential
Tab, a personal AI assistant that emerged from stealth, arrived with a $300 million valuation, as TechCrunch reported. The company announced its emergence from stealth on the Tuesday covered by that report. What stands out is the ratio: a newly visible consumer assistant carrying a valuation in the hundreds of millions before it has the kind of public track record that would normally accompany that number. That is consistent with how consumer AI is being priced in 2026 - on the size of the addressable habit rather than on current revenue. For US consumers, the effect is a crowded field of assistants competing on onboarding and retention, with funding available to subsidise that competition. For US technology companies, it means consumer distribution remains a contested prize, and the incumbents that already own a daily habit have a structural advantage that fresh capital alone does not erase.