The AI Stack Is Fragmenting Into Four Layers
Article

The AI Stack Is Fragmenting Into Four Layers

AI is no longer one product but a stack of distinct businesses, and the winners will be whoever controls the layer they actually sit in.

NagiOctober 7, 20265 min read

Photo: Engadget

The pattern hiding in four unrelated stories

Four stories logged on this desk this week look unrelated: a Google game-creation tool, a partner's adoption dashboard, a rack-scale infrastructure partnership, and a ten-person food delivery startup. They are not unrelated. Each describes a company competing not in "AI" but in one specific layer of it, and each layer has different economics, different competitive dynamics, and different definitions of winning. The AI market has quietly stopped being one market.

Layer one: creation moves to the platform

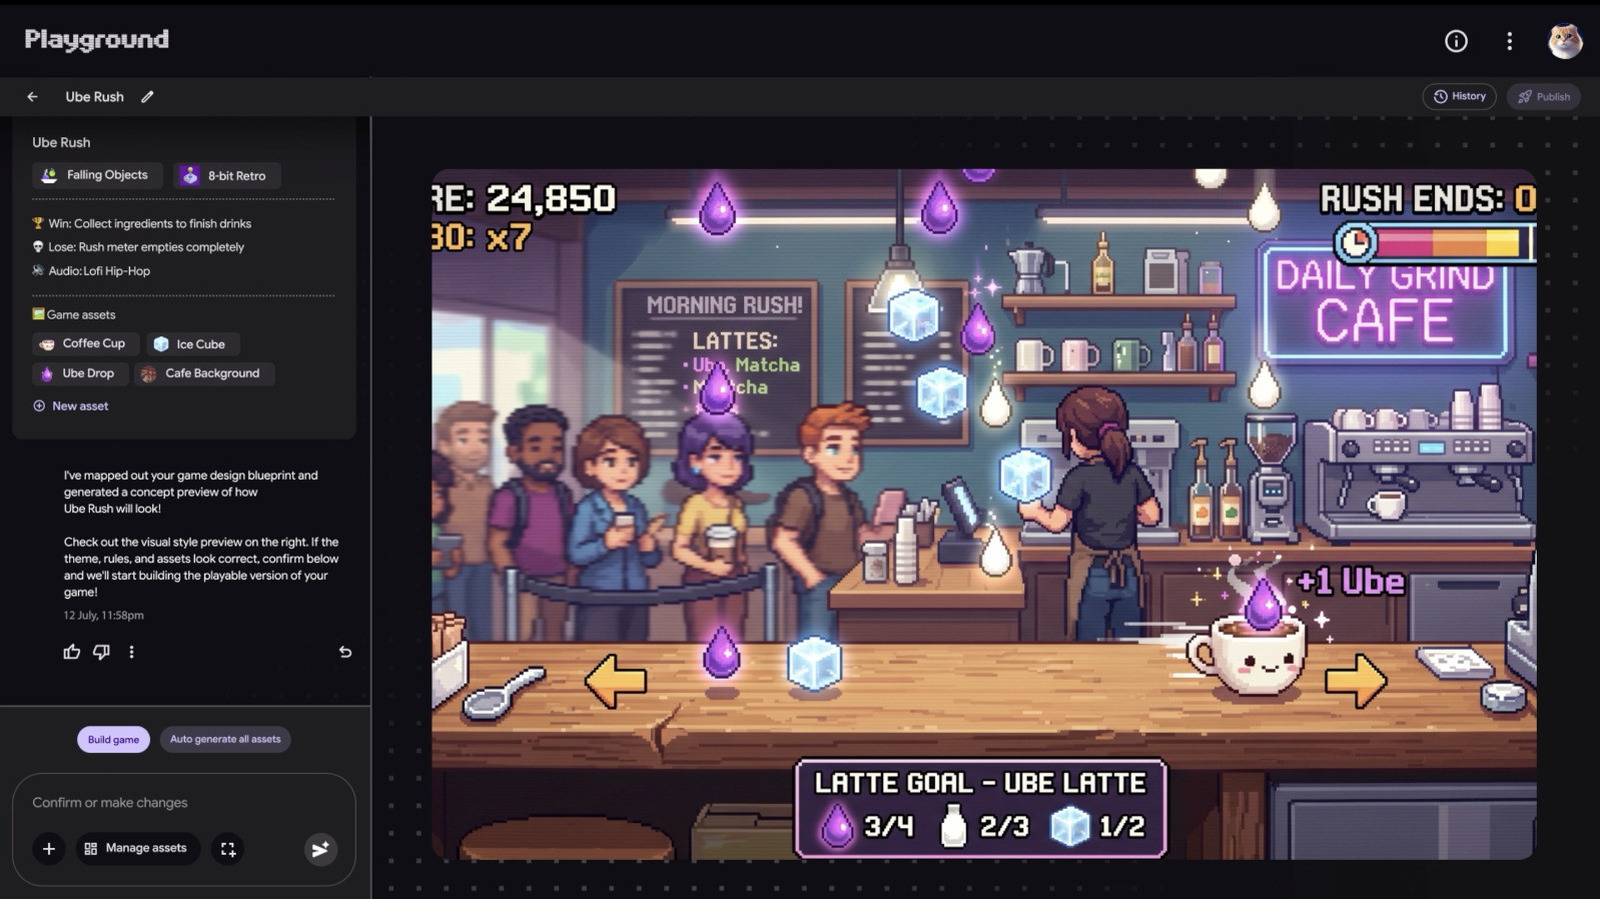
Google's experimental Playground platform uses AI to create games for you, as Engadget reported. The interesting detail is not that AI can generate games. It is who is doing the generating and where. When a platform owner ships a creation tool, the tool becomes a feature of the platform rather than a product in its own right. That has been the recurring pattern in US consumer software for two decades: infrastructure gets commoditised by the platform that sits above it.

For US developers, this cuts both ways. It lowers the cost of producing interactive software, which expands the pool of people who can ship something. It also means that a category of independent tooling companies built around the same capability now competes with something bundled for free by an incumbent that already owns distribution. The strategic question for any US software firm in 2026 is not whether AI can do the thing. It is whether the thing is a product or a checkbox.

Layer two: measurement becomes the product

Promevo launched Insights by Promevo, a platform for tracking adoption of Google's Gemini Enterprise, the AI agents employees build with it, and spending across the rest of a customer's Google Cloud environment, as SiliconANGLE reported. The company frames the problem as a visibility gap.

That framing is the tell. Enterprises have bought AI agents faster than they have built the instrumentation to know what those agents are doing or what they cost. A partner stepping into that gap is not selling intelligence. It is selling accounting. This is a classic second-wave business: the first wave sells capability, the second wave sells the ability to see what the capability is doing.

US enterprise buyers should read this as a signal about maturity. Adoption dashboards do not appear around technologies that are still speculative. They appear when spending has become large enough, and diffuse enough, that finance departments start asking questions. The commercial opportunity here is real but derivative. It exists because someone else's AI deployment is messy. If AI deployment stops being messy, this layer thins out.

Layer three: infrastructure is now a coordination problem

SiliconANGLE also reported that Dell's partnership with CoreWeave has helped the company adapt successive generations of rack-scale systems to different facilities, with reliability depending on how well compute, networking, power and cooling operate together. Sarat Krishnan, a director at Dell, framed the challenge around turning early hardware breakthroughs into repeatable deployments through coordination across engineering, manufacturing and operations.

That is a notable shift in what "AI infrastructure" means. The hard problem is no longer the chip. It is the facility, the power contract, the cooling loop, the deployment playbook, and the ability to repeat all of it in the next building. This is physical, capital-intensive, and stubbornly local.

For the US market specifically, that has consequences. Data centre capacity in the United States is constrained by power availability and by the pace at which facilities can be built and fitted out, not by accelerator supply alone. Companies whose advantage rests on repeatable deployment methodology are building moats out of operational competence rather than technical novelty. Those moats are slower to build and slower to erode.

Layer four: the application layer is still wide open

The Verge reported that DoorDash processed 970 million orders in its second quarter and generated $4.5 billion in revenue, while a ten-person startup called Bites has around 300 restaurants signed up in the Bay Area and is operating as a pre-seed company. The scale gap is roughly what you would expect. What matters is that a startup that small is being written about at all.

Food delivery is not an AI story on its face. It is a story about how thin the application layer still is relative to the platforms beneath it. DoorDash's position rests on logistics density, courier supply, and restaurant relationships accumulated over years. Those are not things a model can generate. A small entrant can compete on a narrow geography and a specific restaurant set precisely because the incumbent's advantage is depth in a market, not possession of a technology.

This is the counterweight to the first three layers. As creation tools, measurement tooling, and infrastructure get absorbed by platforms and incumbents, the place where new US companies can still establish something is the application layer, where the work is unglamorous and the assets are physical and relational.

What this means for US technology companies

The practical implication is that "AI company" is now an unhelpful description. A US firm needs to know which layer it occupies and whether that layer is consolidating or opening. Creation tools sold to consumers are consolidating into platforms. Adoption and cost visibility is a real but transitional business. Infrastructure is consolidating around operators who can repeat deployments across constrained facilities. Applications remain fragmented and therefore contestable.

Misreading the layer is the most common strategic error available right now. A company that thinks it is in the AI business when it is really in the measurement business will over-invest in capability. A company that thinks it is in the model business when it is really in the facilities business will under-invest in operations. The four stories above are, in effect, four different answers to the same question about where value accrues.

What to watch

Three things follow directly from the material above. First, whether Google's Playground, as Engadget described it, remains experimental or becomes a bundled default; that determines whether independent creation tooling in the US has room. Second, whether Promevo's adoption-tracking business, per SiliconANGLE, attracts imitators across other cloud ecosystems, which would confirm that AI spend visibility is a durable category rather than a temporary gap. Third, whether Dell and CoreWeave's deployment work, also per SiliconANGLE, produces a repeatable template that other facility operators can copy, or stays a bespoke advantage.

And beneath all of it, the scale contrast The Verge drew between DoorDash and Bites is the reminder worth keeping: in the application layer, being small is not automatically fatal. Everywhere else, it increasingly is.

More on this beat: AI on TechManNews.

#AI strategy#enterprise AI#AI infrastructure#platform economics#US technology market#application layer

Newsletter

Get Tech News in Your Inbox

The latest AI, gadgets, software and startup stories from TechManNews, delivered every morning - free.