The startup funding market on this beat is not tightening or loosening so much as sorting. Three deals logged in recent days - Ramp's $1.85 billion raise, Intero Biosystems' Startup Battlefield win at Disrupt 2026, and 120ft's 576,000 euro angel round - sit at wildly different points on the capital curve, yet each points to the same underlying shift: money is moving toward companies that pair a software layer with something physical, regulated or operationally hard. The days when a generic SaaS pitch could command a mega-round appear to be giving way to a more selective regime in which the size of a check tracks the difficulty of the problem being solved.
The Mega-Round Goes to the Platform Play
Ramp Business Corp. announced a $1.85 billion Series G led by Dragoneer, with Thrive Capital, Founders Fund, Sands Capital and Avenir Growth as co-leads and contributions from two dozen other investors, according to SiliconANGLE. The round values the corporate credit card and business software provider at $60 billion. What matters for the startups beat is not the headline number but the stated purpose: the company is expanding beyond finance software. In other words, the largest check in this set is going to a company that already has a captive user base and is using new capital to broaden its product surface rather than to find product-market fit.
That is a pattern worth naming. At the top of the market, capital is no longer a discovery mechanism; it is an expansion mechanism. Investors are willing to write enormous checks when a company can point to an existing franchise and a credible path to selling more into it. For US enterprise customers, that dynamic tends to cut both ways: consolidation can simplify procurement, but it also concentrates pricing power in fewer vendors. For US startups below the top tier, the implication is blunter - the mega-round is now a reward for platform adjacency, not a substitute for traction.
The Science Bet Gets a Public Stage
At the other end of the visibility spectrum, TechCrunch reported that Intero Biosystems beat 199 other Startup Battlefield companies to take home the $100,000 grand prize at Disrupt 2026. The dollar figure is trivial next to Ramp's round, and that is precisely the point. A competition win is not capital; it is signal. In life sciences and other deep-tech categories, the binding constraint is rarely a lack of seed money. It is validation from people who can judge whether the underlying science actually holds.
For US technology companies watching this beat, the Disrupt outcome is a reminder that the most capital-intensive, longest-horizon startups still rely on reputational currency that no round can buy outright. A $100,000 prize does not fund a lab, but it can unlock conversations with investors who would otherwise discount a pre-revenue science company. The concentration of 200 competitors into a single winner also says something about the supply side: the pipeline of science-forward startups remains deep, and the selection mechanism remains brutal.
The Hardware Bet Still Runs on Angels
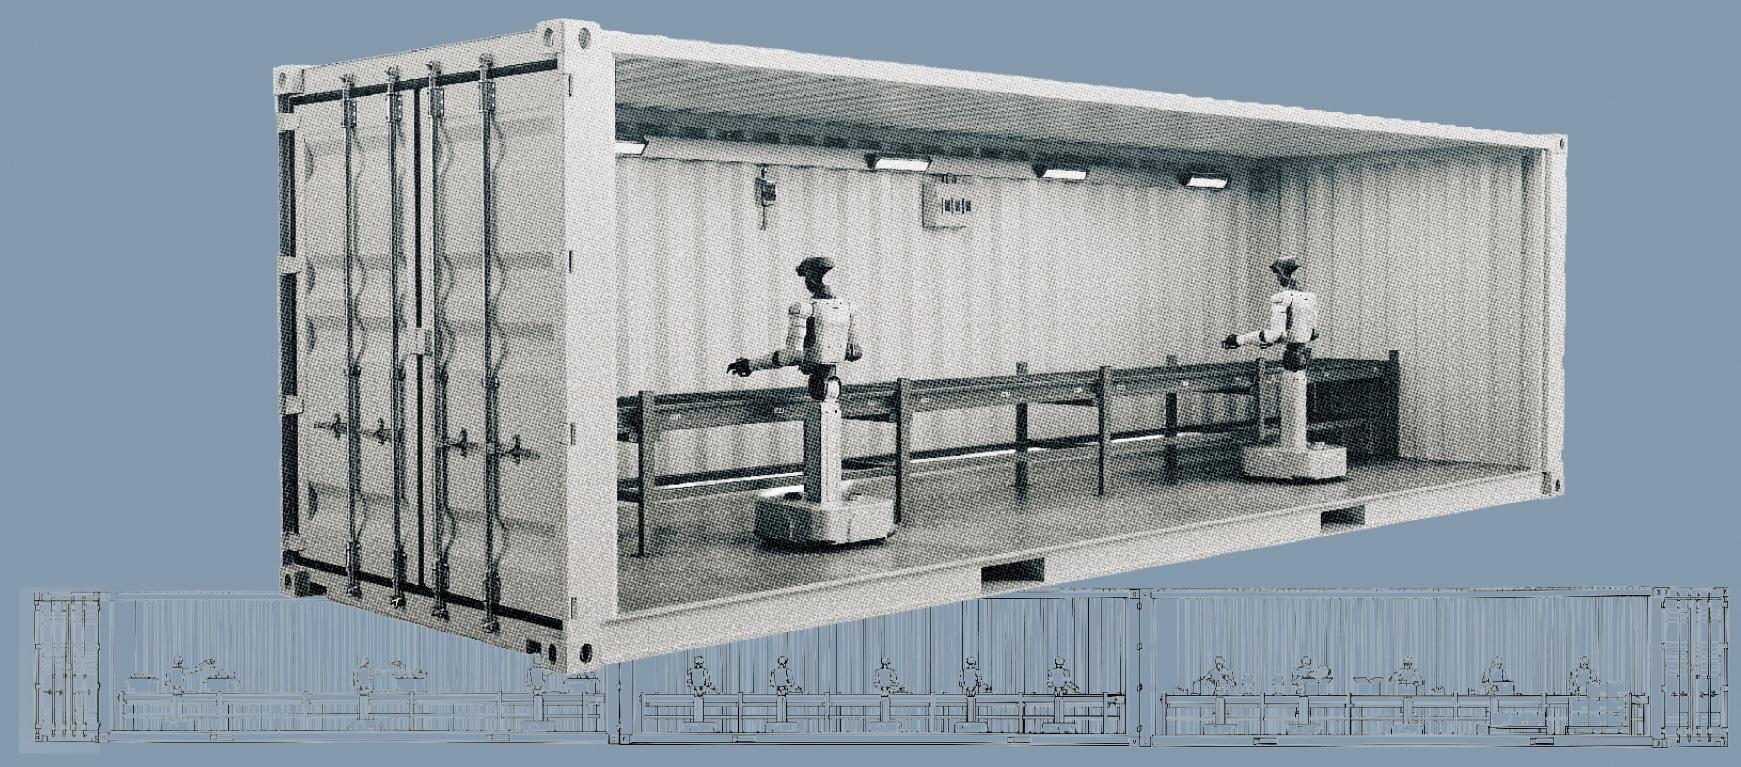
The third story is the most instructive about where the middle of the market is. Swedish robotics startup 120ft Factory AB launched with 576,000 euros, roughly $644,000, from 22 angel investors, according to SiliconANGLE. The company builds and operates small factories that fit inside three 40-foot shipping containers, run by humanoid robots, and it takes its name from the combined length of those containers. Customers never buy the factories outright, the report notes, which makes this an operations business dressed as a hardware company.
That distinction explains the round size. A startup selling containerized microfactories has to prove manufacturing, deployment, maintenance and utilization economics before venture capital will price it at scale. Angel money is the right instrument for that stage, and 22 angels is a structure that buys more than cash - it buys a network of operators who may become early customers. For the US market, this is the category to watch closely, because autonomous microfactories threaten to relocate a slice of light manufacturing closer to demand. If that works, it compresses supply chains that US companies have spent years trying to de-risk.